Case study
Owning Equipment Lease Portfolio Administration
Administration and Transformation at a $2.5 Billion Construction Materials Producer
At a $2.5 billion US construction materials producer, I built the equipment lease portfolio administration from nothing and then renegotiated the financing behind it. The work brought every lease into one system of record, moved payment to Treasury, and established a policy that ended local acquisition in isolation. I led the program in-house as Treasury Manager, and later ran the same process while leading the treasury post-merger integration of an acquisition that roughly doubled the US business. Cleanup actions recovered a one-time $750,000 and ended $170,000 a year in late fees. I also leveraged economies of scale, preferred bank relationships, and bonus depreciation to achieve spread reductions from 128 basis points over benchmark historically to only 14 basis points on new leased equipment.
The role I created is still staffed today, twenty years on.
Delivered as an employee, not through Fractional Transformation LLC.
Business challenge
The corporate treasurer had reached an unusual conclusion: the $620 million equipment lease portfolio in the US operation was in dire need of someone to own it. I happened to be available for reassignment and the opportunity was offered to me. Despite having no experience with equipment leasing, I accepted. There was no one inside the organization to train me. I learned on the fly, calling lessors and asking them to explain their own product.
The portfolio was dispersed across geographies, asset classes and operational areas. Ready-mix trucks and over-the-road tractors and trailers were sourced through a procurement contract, but lease financing was left with the transportation department — who excelled at operations management and were out of their depth on financing. Facilities were negotiated with non-relationship lessors at spreads inconsistent with the company's credit rating. Construction and materials handling equipment was acquired locally, with aggregate facilities and ready-mix plants permitted to sign their own lease documents. Predictable problems followed around budget control, accounting visibility and cost.
My first deliverable was not a negotiation; it was an inventory. Finding the leases meant working backwards through accounts payable disbursement records and calling lessors directly. One thing emerged early and has been true of every portfolio I have looked at since: the lessor relationship is the thread. Pull it and the rest comes with it.
The goal was deliberately narrow — not to change anything, but to know what we had. Fully captured, it ran to 6,808 leased assets across 707 schedules with 26 lessors: $620 million of original equipment cost, and $7.1 million going out the door every month.
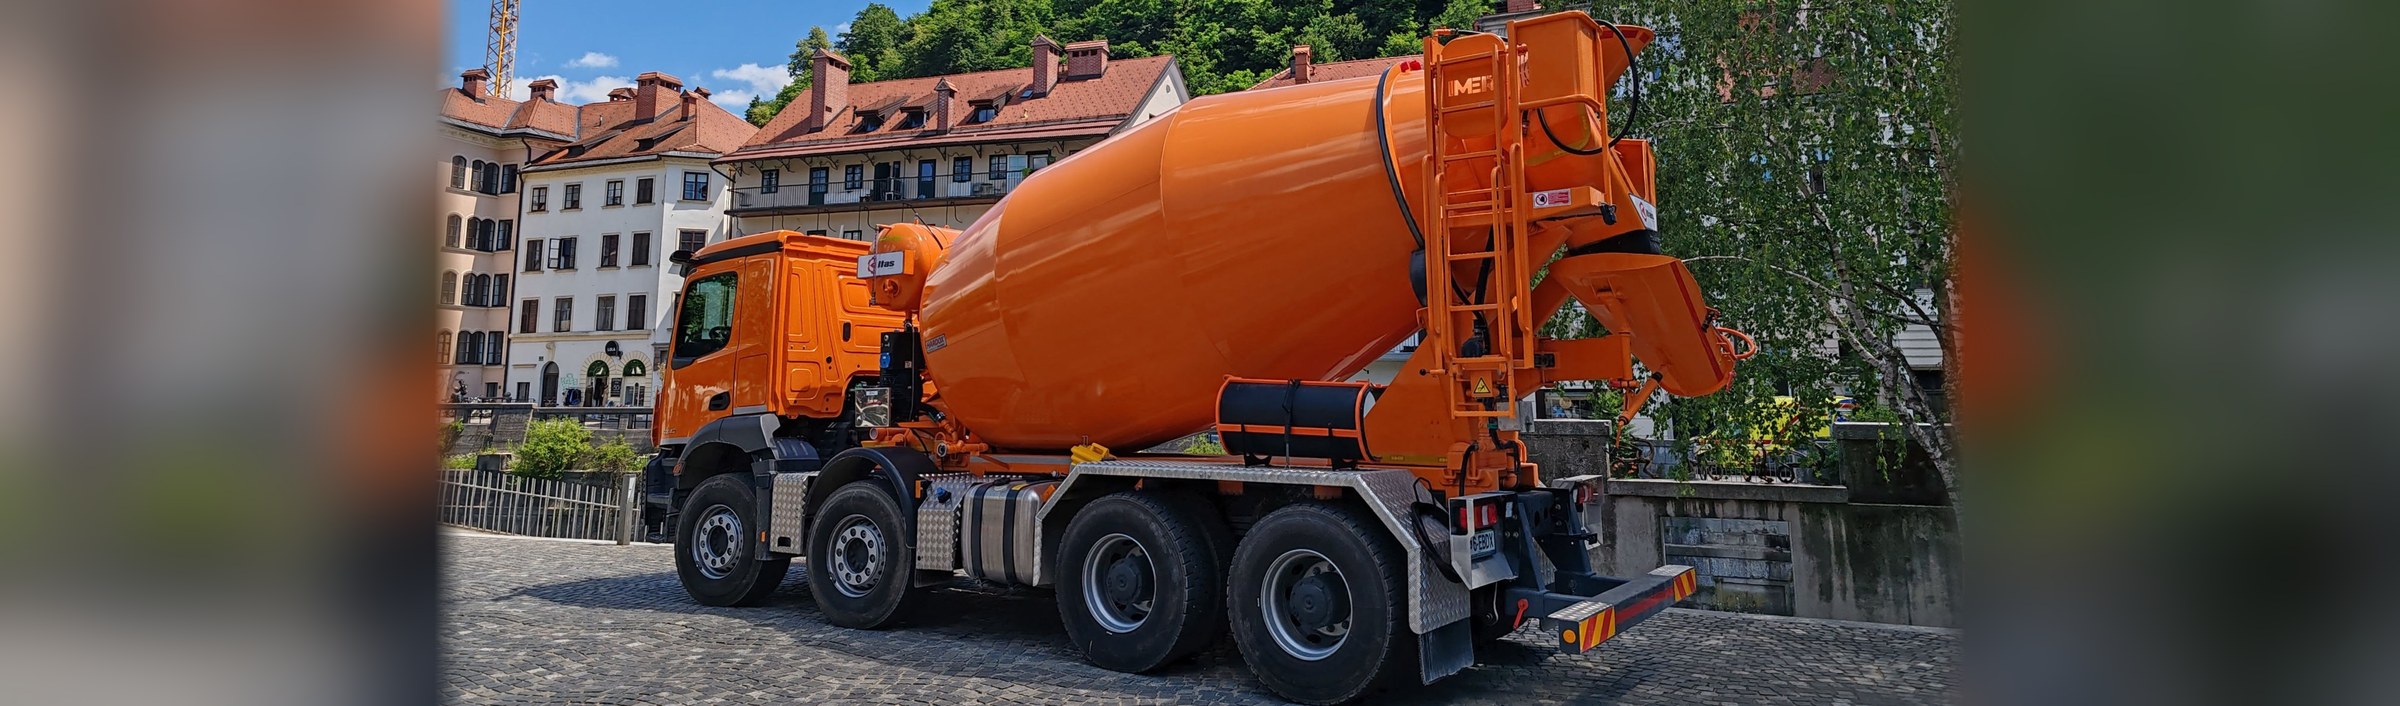
The mix ran the full range: ready-mix mixer trucks and railcars, quarry and earthmoving equipment, over-the-road tractors and trailers, batch plants and aggregate facilities, river barges, materials handling equipment at the plants, and the copiers and printers in the offices.
Program design
System of record, payments and control
Every lease went into the treasury management system, with a module built to hold the lease data. Each asset carried its start and maturity dates, cost, implied rate, lessor, serial number, location, monthly payment, end-of-term option, notice date and general ledger account — everything needed to manage a lease from cradle to grave, in one database. The system also addressed compliance concerns by producing lease accounting entries for the ERP.
Treasury also assumed responsibility for issuing electronic payment each month against the contractual obligation in the lease rather than an invoice. A lease payment is due on the same date every month whether or not an invoice turned up or a local approver was at their desk. That change ended $170,000 in late fees outright.
The equipment lease policy
The system of record gave visibility. The next step was alignment. I worked with a cross-functional team to develop an equipment lease policy covering roles, responsibilities and timing, and establishing Treasury at the core of the process. It was widely communicated, accepted and effective — and was subsequently adopted by corporate treasury as the global standard.
A database tells you what you have. A policy decides who may commit the company. One is a reporting improvement and the other is a control, and only the second one holds.
Integration
In 2005 the company made an acquisition that roughly doubled the size of its US operations. I led the treasury post-merger integration and ran the same process across the acquired portfolio: find everything, clean it up, move it into the same system, pay it from there.
The acquired business had already had a committed annual lease line to an incumbent bank. Within days of the deal closing, I was able to get the pricing on the line reduced by forty basis points. That is the clearest single illustration of what centralized visibility and control are worth: the same bank was now looking at a combined relationship, and someone was there to apply the leverage.
Lease financing
With the portfolio visible and controlled, focus shifted to cost. Over the seven years before anyone owned it, the portfolio had been priced at about 128 basis points over the three-year swap rate — a volume-weighted average across every transaction, measured on the day each one was written.
Two moves followed. New volume was concentrated with a short list of relationship lessors, to build share of wallet and the escalation leverage that comes with it. And the annual requirement was bid as a committed program rather than deal by deal, which gave bidders a volume worth pricing for.
By 2006 that program was $140 million, placed across a handful of relationship lessors, and the RFP took 55 to 66 basis points out of the pricing — worth $800,000 to $900,000 a year — while also removing the financial covenants.
End of term, and the successor
A common record and an end-of-term calendar centralized expiration tracking, notice dates, returns and replacement decisions, and gave Accounting the complete lease population it had never had.
Finally, I trained a successor — not as a courtesy, but because a portfolio without an owner reverts. Twenty years later, lease administration continues to have a dedicated resource in the company's treasury department.
Results
One-time cleanup savings are rarely the result of discovering hidden opportunities. They come from someone taking the time to resolve issues many people are aware of and nobody owns — evergreen leases, open balances from cash application errors, insurance charged because the certificate was never provided. On a portfolio this size, cleanup alone returned about $750,000 and paid for the cost of a lease administration role for years.
What ownership did to the pricing
Volume-weighted spread over the three-year swap rate, measured on the day each transaction was written.
Scroll sideways to see all three periods.
In total, the lease pricing negotiations produced approximately $1.7 million a year in recurring savings, against $385 million of new lease originations written between 2003 and 2006.
The same controls and competitive process were then extended across the remaining asset classes — railcars, fleet vehicles and small-ticket equipment — each producing further savings.
Four questions for your own portfolio
Who owns the program. Not the equipment — the program.
Procurement negotiates the purchase, operations runs the asset, finance decides whether to buy or lease, and accounts payable pays for it. Each function owns its piece, correctly. If no one owns the whole, no one is positioned to see big picture opportunities.
The end of lease process. Who is managing notice dates and the end of lease process?
Are local operations expected to manage equipment returns without support? How many units are in evergreen status?
The payment route. Are lease payments reconciled centrally by someone with context to know whether they should be paid?
Are they paid based on contractual obligation regardless of invoice receipt or local approval?
The reversion test. If the person who knows the most about your equipment leases left tomorrow, what would stop the program drifting back to local practice within a year?
If these answers are difficult to obtain, a focused diagnostic can establish the lease population, identify the largest cost and control gaps, and determine whether taking ownership of the portfolio would produce a worthwhile return.